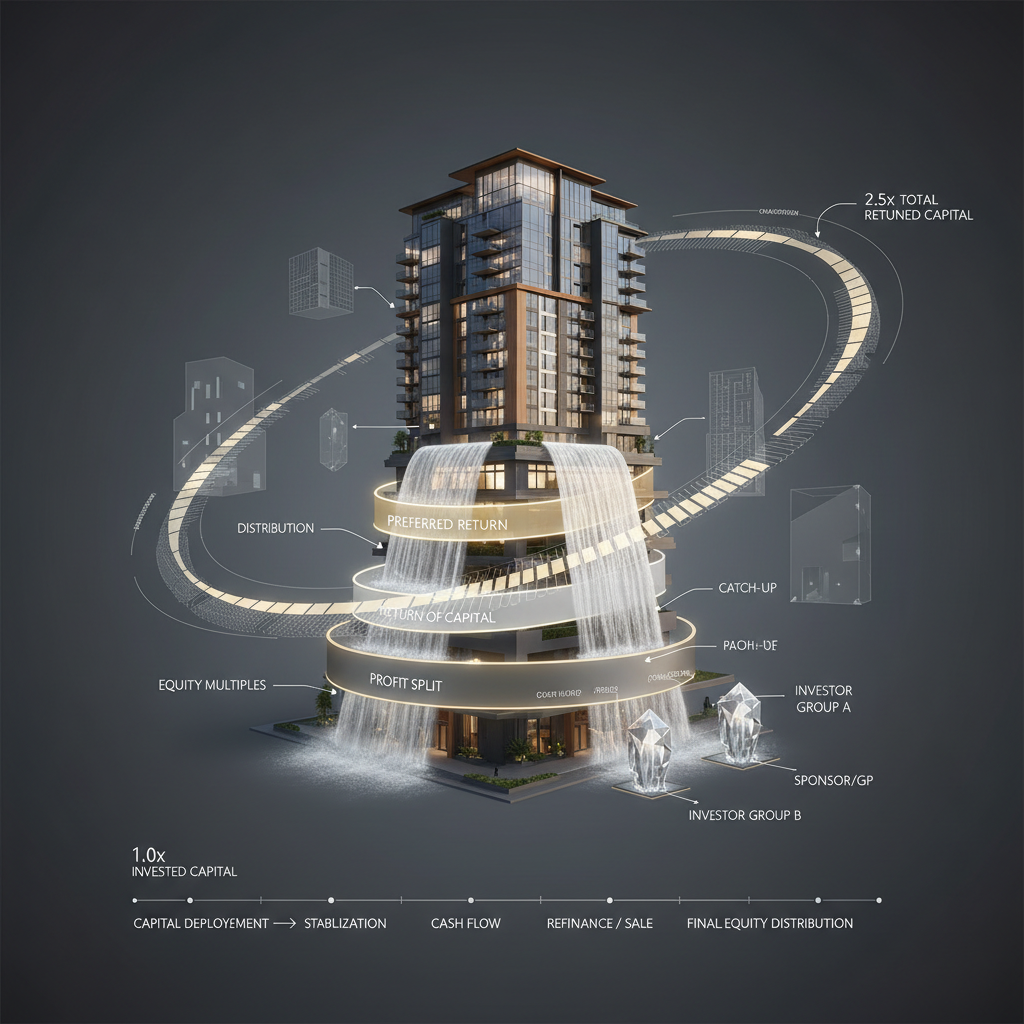
Equity Multiples, Waterfalls, and Preferred Returns: A Plain English Guide
FAM Capital | Investor Education Series
If you’re going to invest passively in real estate, especially through syndications, you’re going to encounter three terms over and over again: equity multiple, preferred return, and waterfall. These concepts determine how the money flows in a deal, who gets paid first, and how profits are split between investors and the sponsor.
Most people’s eyes glaze over when these terms come up because they sound like Wall Street jargon. They’re not. The ideas behind them are straightforward once someone explains them in plain language instead of burying them in legal documents and footnotes.
This article is going to break down all three concepts so you understand exactly what each one means, why it matters to you as an investor, and what to look for (and look out for) when reviewing a deal. By the end, you’ll be able to read the economic terms of a syndication offering and understand precisely how your money is being treated.
Equity Multiple: Your Total Return, Start to Finish
The equity multiple is the simplest return metric in real estate. It tells you how much total money you’re getting back relative to what you put in, over the entire life of the deal. That’s it.
The formula is: Equity Multiple = Total Distributions Received / Total Capital Invested
If you invest $100,000 and over the course of the deal you receive a total of $180,000 (including all cash flow distributions plus your original capital returned at sale or refinance), your equity multiple is 1.8x. If you receive $200,000, it’s 2.0x. If you receive $250,000, it’s 2.5x.
Think of it like holding a bond to maturity. When the deal is done and all the money has been returned, the equity multiple tells you what the total outcome was. You put in a dollar, and when it was all said and done, you got back a dollar eighty, or two dollars, or two fifty. It’s the clearest, most honest measure of total return.
Why Equity Multiple Matters
The equity multiple grounds the conversation in real dollars. Unlike IRR, which can be manipulated by timing, the equity multiple simply answers the question: how much money did I make? A 2.0x multiple means you doubled your money. A 1.5x means you made 50% on your investment. There is no complexity to hide behind.
This is why experienced investors look at equity multiple alongside IRR rather than relying on either one alone. A deal might project a strong IRR because capital comes back quickly, but if the equity multiple is only 1.4x, the total profit isn’t that impressive. Conversely, a deal with a moderate IRR but a 2.2x equity multiple is putting significantly more total dollars in your pocket, even if it takes longer.
A 2.0x over five years is very different from a 2.0x over ten years. The equity multiple tells you the total. The IRR tells you the rate. You need both to fully understand what the deal is offering.
What to Watch For
- Make sure the equity multiple includes the return of your original capital, not just profits on top of it.
- Remember that the projected equity multiple is an estimate; it’s based on the same assumptions that drive every other projection in the pro forma: rent growth, expense control, exit pricing, and hold period.
Preferred Return: The Investor’s Priority
A preferred return (often shortened to “pref”) is a threshold return that investors receive before the sponsor takes any share of the profits. It’s a priority of payment. It means the investors get paid first, up to a certain percentage, before the sponsor participates in any profit split.
A typical preferred return in a syndication is 6% to 8% annually. If the pref is 8%, that means the first 8% of returns on your invested capital goes entirely to you as the investor. The sponsor doesn’t take a share of profits until you’ve received your 8% preferred return. Only after that threshold is met do the profits start splitting between investors and the sponsor.
Why Preferred Returns Matter
The preferred return exists to establish the sponsor’s duty to their investors. It says: before we make any money on the profit split, you the investor are going to be taken care of first. It creates a structure where the sponsor is absolutely, positively responsible to their investors and has every incentive to protect those funds and deliver results.
This is about the relationship between the sponsor and their investors. A sponsor who structures a deal with a preferred return is telling you that they take their obligation seriously. They’re putting your return ahead of their profit participation. That alignment of interests is one of the most important things to look for in any passive investment.
Without a preferred return, the sponsor could start taking their share of profits from dollar one, even if your return is mediocre. With a preferred return, they only get to participate in the upside after you’ve received a reasonable return on your capital.
Preferred Return Is Not a Guaranteed Return
This is a critical distinction that many investors miss. A preferred return is a target, not a guarantee. It’s a priority of payment, meaning if there is money to distribute, you get paid first up to the pref amount. But if the deal underperforms and there isn’t enough cash flow to cover the preferred return, you don’t receive it. Nobody writes you a check for the shortfall out of their own pocket.
The preferred return is only as strong as the deal behind it. A great deal with a great sponsor will likely meet or exceed the pref. A struggling deal might fall short. The pref protects your position in the payment order, but it doesn’t eliminate the risk that the deal underperforms. Understanding this distinction keeps your expectations realistic.
Cumulative vs. Non-Cumulative: A Detail That Matters
Not all preferred returns are structured the same way, and this is a detail that can have a significant impact on your total return. The key distinction is whether the preferred return is cumulative or non-cumulative.
Cumulative Preferred Return
A cumulative preferred return means that if the deal fails to pay the full pref in any given period, the unpaid amount accrues and carries forward. It accumulates. The sponsor cannot participate in any profit split until all accrued, unpaid preferred returns have been made up.
For example, say the deal has an 8% cumulative pref and in year one the property only generates enough cash flow to pay a 5% return. The remaining 3% isn’t gone. It accrues. In year two, before the sponsor takes any profit split, you’re owed the current year’s 8% plus the 3% shortfall from year one. The sponsor doesn’t get to skip past the unpaid pref and start collecting profit.
Non-Cumulative Preferred Return
A non-cumulative preferred return means that if the pref isn’t paid in a given period, that shortfall is gone. It doesn’t carry forward. It doesn’t accrue. The next period starts fresh, and the sponsor can potentially start participating in profit splits even though you were shortchanged in prior periods.
Non-cumulative prefs are less common in syndications, but they do exist. From an investor’s perspective, this is a weaker protection. It means the sponsor can benefit from good periods without making up for bad ones. If you see a non-cumulative pref in a deal, that’s worth a conversation with the sponsor about why they structured it that way.
What to Look For
- Always check whether the preferred return is cumulative or non-cumulative. This information is in the operating agreement or the private placement memorandum.
- If it’s not clearly stated, ask.
- If the deal uses a non-cumulative pref, understand the implications and make sure the overall return profile still makes sense for the risk you’re taking.
As a general principle, cumulative preferred returns provide stronger investor protection and better alignment of interests between the sponsor and the limited partners.
The Waterfall: How Profits Actually Flow
A waterfall is the structure that determines how profits are distributed between investors and the sponsor. It’s called a waterfall because the money flows down through a series of levels, or tiers, with each level having specific rules about who gets paid and how much.
The concept is simple even though the legal language in operating agreements can make it look complicated. Here’s how a basic waterfall works.
How a Simple Waterfall Flows
The first tier is the return of capital. Before anyone receives any profit, investors get their original investment back. If you put in $100,000, the first $100,000 coming your way is simply your own money being returned.
The second tier is the preferred return. Once your capital is being returned (or alongside it, depending on the structure), you receive your preferred return. If the pref is 8%, you’re entitled to an 8% annual return on your invested capital before the sponsor participates in profit splits. If the pref is cumulative and there were any shortfalls, those get made up in this tier as well.
The third tier is the profit split. Once investors have received their capital back and their preferred return, the remaining profits are split between investors and the sponsor according to a predetermined ratio. A common split is 70/30 (70% to investors, 30% to sponsor) or 80/20. This is where the sponsor makes their real money on the deal.
That’s the basic framework. Money flows through these tiers in order. Investors are protected at the top of the waterfall, and the sponsor gets rewarded at the bottom for delivering results.
Why the Waterfall Structure Matters
The waterfall determines the economic relationship between you and the sponsor for the life of the deal. It answers the most fundamental question in any partnership: who gets paid what, and in what order?
A well-structured waterfall rewards the sponsor fairly for their work and expertise while never doing so at the expense of investor returns. The investors’ capital is protected first. The investors’ preferred return comes next. And only after those obligations are met does the sponsor start participating in the upside.
This is the structure that aligns incentives correctly. The sponsor has every reason to perform because their profit is tied to outcomes that exceed the investors’ baseline expectations. If the deal underperforms, the sponsor makes less. If the deal outperforms, both parties benefit, but the investors are always taken care of first.
What Makes a Waterfall Investor-Friendly vs. Sponsor-Friendly
Not all waterfalls are created equal. Some are more favorable to investors and some lean more heavily toward the sponsor. Understanding where a given deal falls on that spectrum is an important part of your due diligence.
An investor-friendly waterfall has a meaningful preferred return (7% to 8% or higher), a cumulative pref structure, return of capital before profit splits, and a profit split that gives investors the majority of remaining profits (70/30 or better).
A sponsor-friendly waterfall might have a lower pref (5% or less), a non-cumulative structure, an early profit split that kicks in before all capital is returned, or a split that heavily favors the sponsor (50/50 or 60/40 to the sponsor). None of these features are inherently disqualifying, but they shift more of the economics to the sponsor and less to the investor.
Some deals use multi-tier waterfalls where the profit split changes as returns exceed certain thresholds. For example, the split might be 80/20 up to a 15% IRR, then shift to 60/40 above that. This rewards the sponsor with a larger share if they deliver exceptional returns, which can be reasonable if the base-level investor protections are strong.
The key principle is simple: the waterfall should reward the sponsor fairly but never at the expense of investor returns. If you look at a waterfall and the sponsor is getting a generous split before investors have received a reasonable return on their capital, that’s a structure that prioritizes the sponsor’s interests over yours.
How These Three Concepts Work Together
Equity multiple, preferred return, and waterfall structure are not separate, independent metrics. They’re interconnected pieces of the same economic puzzle.
The equity multiple tells you the projected total return of the deal. It’s the bottom line: how much money are you expected to receive relative to what you put in.
The preferred return tells you how the early distributions are structured. It establishes that you receive a baseline return before the sponsor participates in profits.
The waterfall tells you how the total profits (the ones that generate the equity multiple) are divided between you and the sponsor. It’s the mechanism that determines whether the projected equity multiple is realistic and whether the sponsor’s incentives are aligned with yours.
When evaluating a deal, you need to look at all three together. A deal might project a 2.0x equity multiple, but if the waterfall heavily favors the sponsor, a significant chunk of that 2.0x is going to the GP, not to you. Understanding the split tells you what your actual multiple is likely to be after the sponsor takes their share.
Similarly, a deal might offer an attractive 8% preferred return, but if the equity multiple is only 1.4x over five years, the total return isn’t that compelling. The pref protects your downside, but the overall deal needs to generate enough profit to make the investment worthwhile.
Sponsor Fees: The Other Piece of the Puzzle
While we’re discussing how money flows in a syndication, it’s worth mentioning sponsor fees because they affect the total economics alongside the waterfall. Most syndication sponsors charge fees on top of the waterfall profit split. Common fees include an acquisition fee (typically 1% to 3% of the purchase price), an asset management fee (1% to 2% of collected revenue or invested equity annually), a construction or renovation management fee, a refinance fee, and a disposition fee at sale.
These fees are paid to the sponsor regardless of how the deal performs. They come off the top, before any distributions to investors. This is how sponsors cover their operational costs and get compensated for the day-to-day work of managing the deal.
Fees aren’t inherently bad. Sponsors are doing real work and deserve to be paid for it. But the fee structure should be reasonable and transparent. If the fees are so high that they eat significantly into investor returns even in a good outcome, the deal may be structured more for the sponsor’s benefit than for the investors. Always review the fee schedule as part of your evaluation and understand how fees impact the projected equity multiple and cash-on-cash return.
Questions to Ask About Deal Economics
When you’re reviewing a syndication offering, here are the questions you should be asking about the economic structure.
- What is the projected equity multiple and over what hold period? This tells you the total expected return on your investment.
- What is the preferred return and is it cumulative? You want to know your priority of payment and whether shortfalls accrue.
- What is the waterfall structure? Understand every tier: return of capital, preferred return, and profit split. Know who gets paid what and in what order.
- What fees does the sponsor charge and when are they collected? Understand how fees impact the net returns to investors.
- What happens if the deal underperforms? Does the pref accrue? Does the sponsor still collect fees? How are losses allocated?
- What are the assumptions driving the projected equity multiple? The multiple is only as reliable as the rent growth, exit cap rate, and expense assumptions behind it.
- Does the sponsor have capital invested alongside the investors? When a sponsor has their own money in the deal, their interests are even more closely aligned with yours because they’re subject to the same risks and the same waterfall.
The Bottom Line
Equity multiples, preferred returns, and waterfall structures are the economic backbone of every syndication deal. They determine how much money you’re projected to make, in what order you get paid, and how profits are divided between you and the sponsor.
The equity multiple tells you total return. The preferred return establishes your priority of payment and reflects the sponsor’s duty to take care of investors first. The waterfall structure determines whether the deal rewards the sponsor fairly while protecting investor returns, or whether the economics tilt too far in one direction.
These are not details to skim over or take at face value. They’re the terms that define your entire economic relationship with the sponsor for the life of the deal. Understand them, ask questions about them, and make sure the structure aligns with your expectations before you invest a dollar.
